EX-99.2
Published on October 28, 2026
Q3 2026 EARNINGS PRESENTATION Jan Jenisch, Chairman and CEO Samuel Poletti, CFO October 29, 2026
2 SAFE HARBOR STATEMENT FORWARD-LOOKING STATEMENTS AND NON-GAAP FINANCIAL MEASURES Certain statements in this presentation may be considered forward-looking statements within the meaning of the Private Securities Litigation Reform Act, such as statements regarding expected cost savings, future financial targets, business strategies, management’s views with respect to future events and financial performance, and the assumptions underlying such expected cost savings, targets, strategies, and statements. Forward-looking statements include those preceded by, followed by or that include the words such as “may,” “will,” “could,” “should,” “might,” “projects,” “expects,” “believes,” “anticipates,” “intends,” “plans,” “continue,” “estimate,” or “pursue,” or similar expressions, or the negative or other variations thereof or comparable terms. Such forward-looking statements are subject to risks, uncertainties and other factors which could cause actual results to differ materially from historical experience or from future results expressed or implied by such forward-looking statements. Potential risks and uncertainties include, but are not limited to, the effect of political, economic and market conditions and geopolitical events; the level of demand in the construction industry; the cyclicality of the industries and businesses in which our customers operate; changes in the cost and/or availability of raw materials required to run our business; energy and fuel costs; adverse weather conditions and natural disasters; the logistical and other challenges inherent in our operations; the actions and initiatives of current and potential competitors; the level and volatility of, interest rates and other market indices; the ability of Amrize to realize the expected synergies for our acquisitions; the ability of Amrize to achieve margin expansion goals; the ability of Amrize to maintain satisfactory credit ratings; the outcome of pending litigation or future litigation; the impact of current, pending and future legislation and regulation; factors related to the failure of Amrize to achieve some or all of the expected strategic benefits or opportunities expected from the separation from Holcim Ltd (“Holcim”); material costs and expenses as a result of the separation from Holcim; our limited history operating as an independent, publicly traded company; our obligation to indemnify Holcim pursuant to the agreements entered into in connection with the separation and the risk Holcim may not fulfill any obligations to indemnify Amrize under such agreements; that under applicable tax law, Amrize may be liable for certain tax liabilities of Holcim following the separation if Holcim were to fail to pay such taxes; the fact that Amrize may receive worse commercial terms from third-parties for services it used to receive from Holcim prior to the separation; the fact that certain of Amrize's executive officers and directors may have actual or potential conflicts of interest because of their previous positions at Holcim; and potential difficulties in maintaining relationships with key personnel; and other factors which can be found in Amrize’s media releases and Amrize’s filings with the SEC. These statements are not guarantees of future performance and are subject to future events, risks and uncertainties – many of which are beyond our control, dependent on the actions of third parties, or currently unknown to us – as well as potentially inaccurate assumptions that could cause actual results to differ materially from our historical experience and our expectations and projections. Any forward-looking statement speaks only as of the date on which it is made. We do not undertake or assume any obligation to update or revise any forward-looking statement, whether as a result of new information, future developments, or otherwise. You are advised, however, to review any further disclosures we make on related subjects in our filings with the Securities and Exchange Commission and in our other public statements. Amrize reports its financial results in accordance with accounting principles generally accepted in the United States (“GAAP”). We have supplemented the reporting of our financial information determined in accordance with GAAP with certain Non-GAAP (or adjusted) financial measures, including Adjusted EBITDA, Adjusted EBITDA Margin, Segment Adjusted EBITDA, Segment Adjusted EBITDA Margin and Net Leverage Ratio. Reconciliations of Non-GAAP measures used in this presentation to the most directly comparable U.S. GAAP measures are included below under “Appendix.” We believe these adjusted financial measures facilitate analysis and comparisons of our ongoing business operations because they exclude items that may not be indicative of, or are unrelated to, the Company’s and our business segments’ core operating performance, and may assist investors with comparisons to prior periods and assessing trends in our underlying businesses. These adjustments are consistent with how management views our businesses. Management uses these Non- GAAP financial measures in making financial, operating and planning decisions, and evaluating Amrize’s and each business segment’s ongoing performance. Note that the definitions of these Non-GAAP financial measures may differ from those terms as defined or used by other companies. This presentation should be reviewed in conjunction with our third quarter fiscal 2026 earnings release and webcast of the earnings presentation conference call, which are available on Amrize’s website at investors.amrize.com.
3 Winthrop Center, Boston, MA Amrize inside Q3 2026 HIGHLIGHTS Jan Jenisch, Chairman and CEO
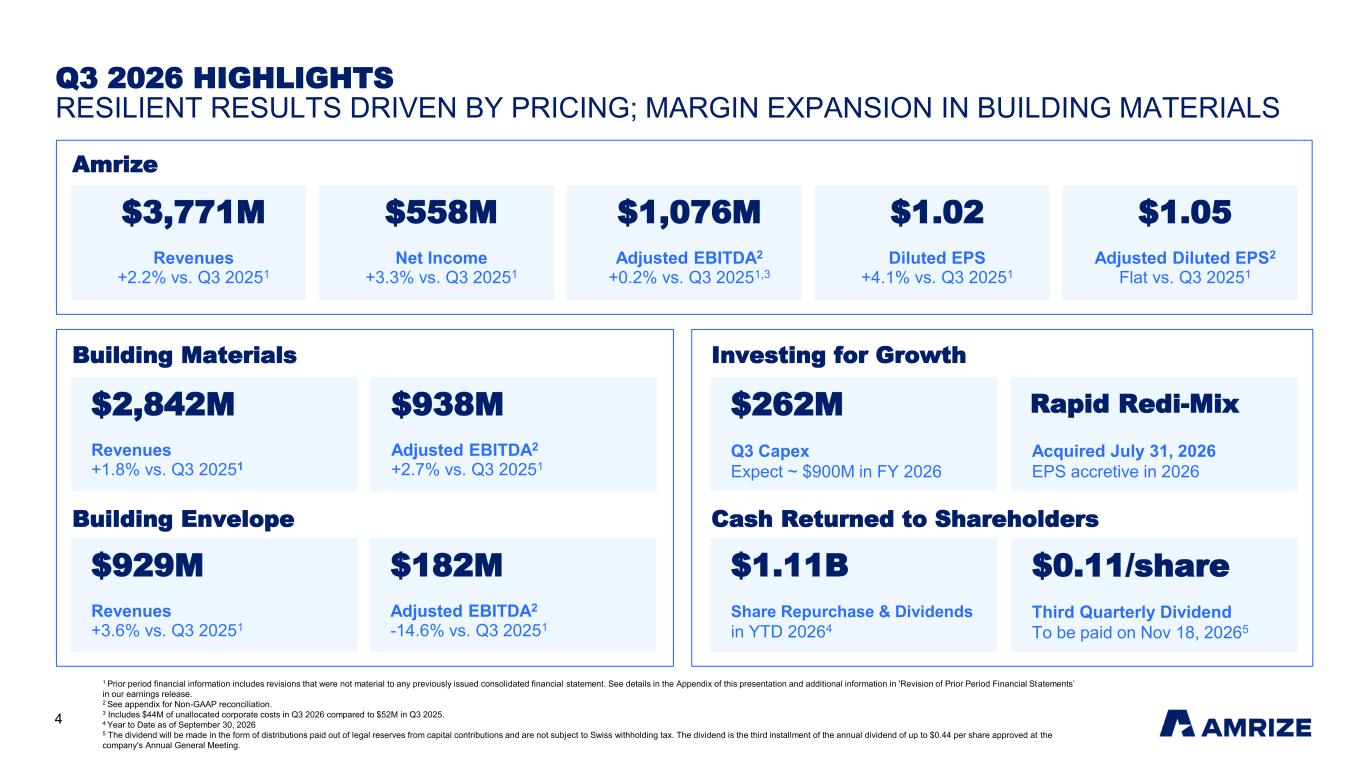
4 Q3 2026 HIGHLIGHTS RESILIENT RESULTS DRIVEN BY PRICING; MARGIN EXPANSION IN BUILDING MATERIALS 1 Prior period financial information includes revisions that were not material to any previously issued consolidated financial statement. See details in the Appendix of this presentation and additional information in 'Revision of Prior Period Financial Statements’ in our earnings release. 2 See appendix for Non-GAAP reconciliation. 3 Includes $44M of unallocated corporate costs in Q3 2026 compared to $52M in Q3 2025. 4 Year to Date as of September 30, 2026 5 The dividend will be made in the form of distributions paid out of legal reserves from capital contributions and are not subject to Swiss withholding tax. The dividend is the third installment of the annual dividend of up to $0.44 per share approved at the company's Annual General Meeting. $2,842M Revenues +1.8% vs. Q3 20251 $938M Adjusted EBITDA2 +2.7% vs. Q3 20251 $929M Revenues +3.6% vs. Q3 20251 $182M Adjusted EBITDA2 -14.6% vs. Q3 20251 Building Materials Building Envelope $3,771M Revenues +2.2% vs. Q3 20251 $1,076M Adjusted EBITDA2 +0.2% vs. Q3 20251,3 Amrize $262M Q3 Capex Expect ~ $900M in FY 2026 Acquired July 31, 2026 EPS accretive in 2026 Investing for Growth $558M Net Income +3.3% vs. Q3 20251 $1.05 Adjusted Diluted EPS2 Flat vs. Q3 20251 $1.02 Diluted EPS +4.1% vs. Q3 20251 $1.11B Share Repurchase & Dividends in YTD 20264 $0.11/share Third Quarterly Dividend To be paid on Nov 18, 20265 Cash Returned to Shareholders Rapid Redi-Mix
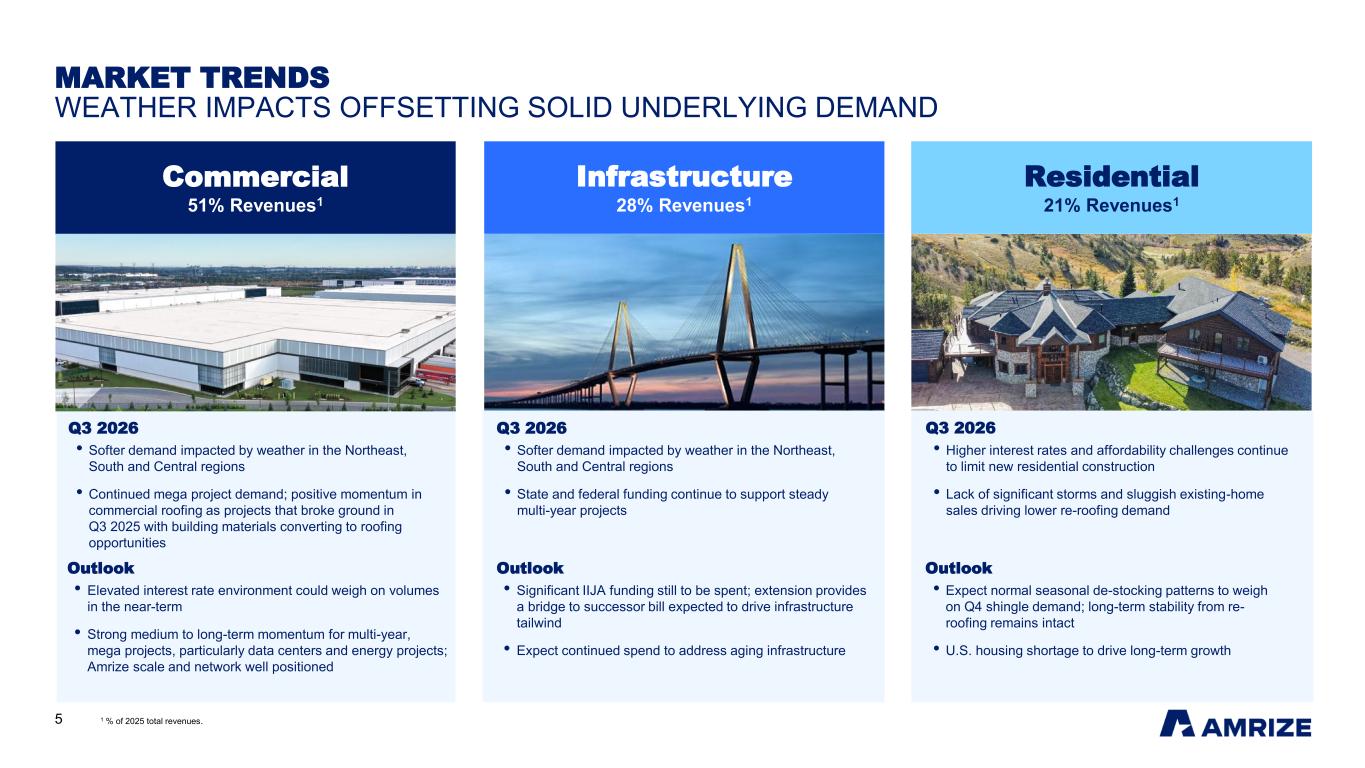
5 Commercial 51% Revenues1 Infrastructure 28% Revenues1 Residential 21% Revenues1 MARKET TRENDS WEATHER IMPACTS OFFSETTING SOLID UNDERLYING DEMAND 1 % of 2025 total revenues. Outlook • Elevated interest rate environment could weigh on volumes in the near-term • Strong medium to long-term momentum for multi-year, mega projects, particularly data centers and energy projects; Amrize scale and network well positioned Q3 2026 • Softer demand impacted by weather in the Northeast, South and Central regions • Continued mega project demand; positive momentum in commercial roofing as projects that broke ground in Q3 2025 with building materials converting to roofing opportunities Outlook • Significant IIJA funding still to be spent; extension provides a bridge to successor bill expected to drive infrastructure tailwind • Expect continued spend to address aging infrastructure Outlook • Expect normal seasonal de-stocking patterns to weigh on Q4 shingle demand; long-term stability from re- roofing remains intact • U.S. housing shortage to drive long-term growth Q3 2026 • Higher interest rates and affordability challenges continue to limit new residential construction • Lack of significant storms and sluggish existing-home sales driving lower re-roofing demand Q3 2026 • Softer demand impacted by weather in the Northeast, South and Central regions • State and federal funding continue to support steady multi-year projects
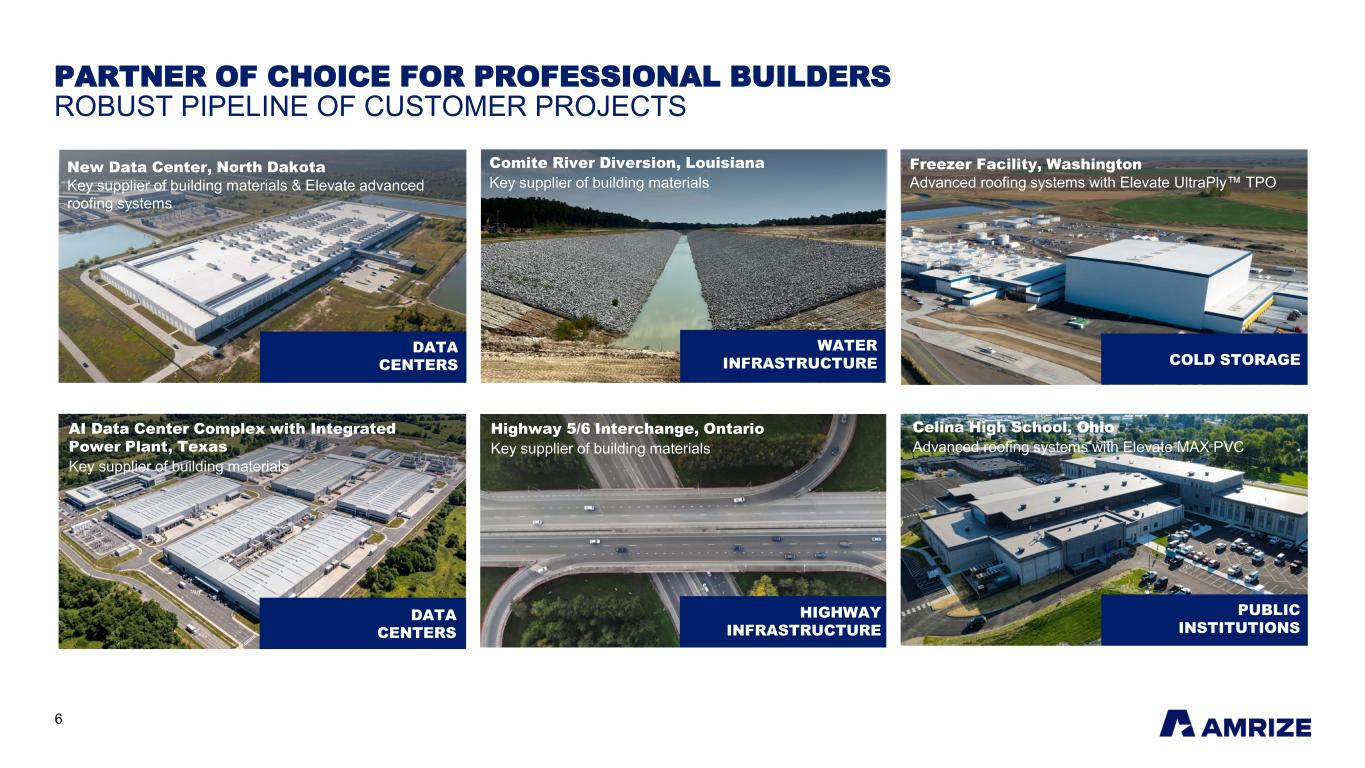
6 PARTNER OF CHOICE FOR PROFESSIONAL BUILDERS ROBUST PIPELINE OF CUSTOMER PROJECTS New Data Center, North Dakota Key supplier of building materials & Elevate advanced roofing systems DATA CENTERS AI Data Center Complex with Integrated Power Plant, Texas Key supplier of building materials DATA CENTERS WATER INFRASTRUCTURE Comite River Diversion, Louisiana Key supplier of building materials Highway 5/6 Interchange, Ontario Key supplier of building materials HIGHWAY INFRASTRUCTURE Freezer Facility, Washington Advanced roofing systems with Elevate UltraPly TPO COLD STORAGE PUBLIC INSTITUTIONS Celina High School, Ohio Advanced roofing systems with Elevate MAX PVC
7 Accelerating Synergies and Partnerships for Impact and REsults ASPIRE PROGRAM ON TRACK $73 MILLION IN SAVINGS DELIVERED YTD 2026 ✓ $73M in savings delivered YTD 20261 ✓ Executing projects with cost savings across raw materials, services, logistics and equipment; ~1,000 suppliers onboarded in 2026 ✓ Success stories include optimized vendor mix for raw materials, services and quarry equipment; leveraging our economies of scale in logistics for both segments ✓ On track to achieve ~$80M of savings in 2026 ✓ On track to achieve $250M of savings through 2028 1 Year to Date as of September 30, 2026
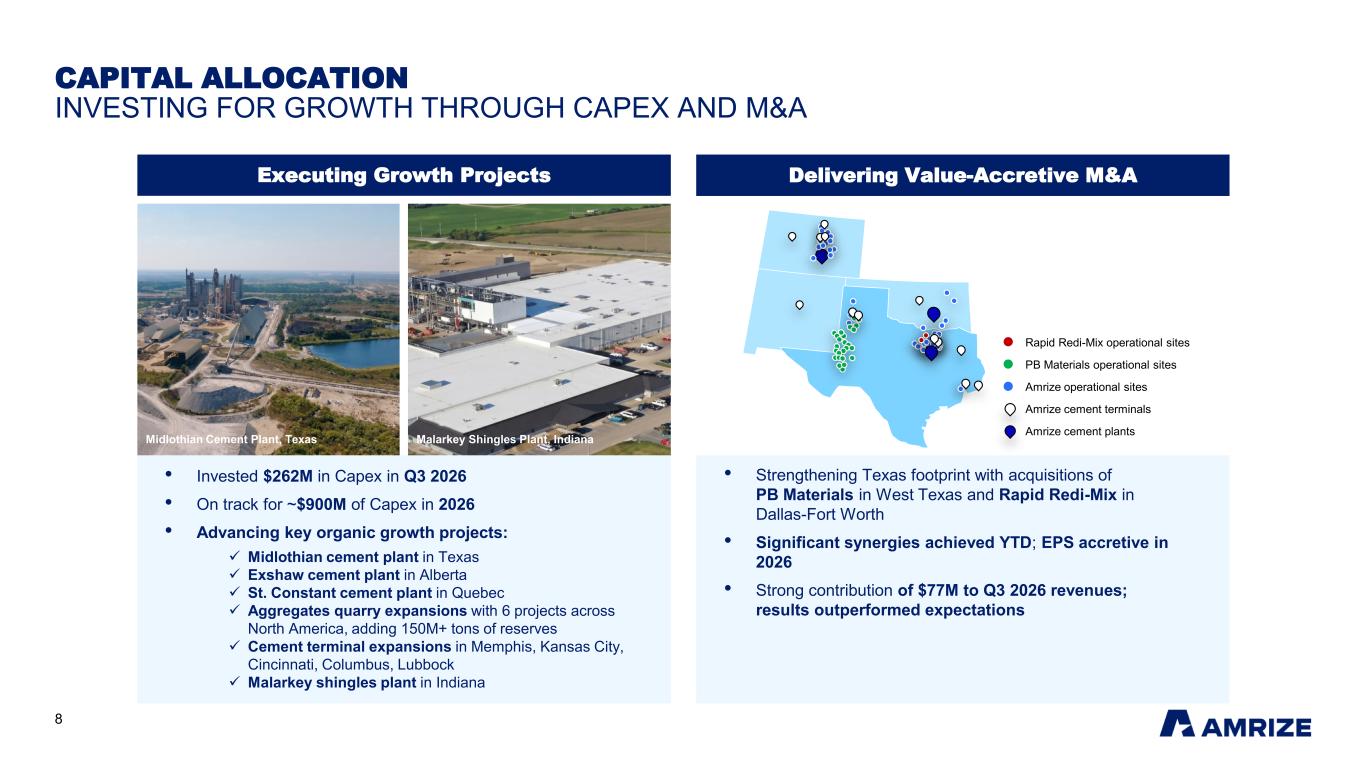
8 CAPITAL ALLOCATION INVESTING FOR GROWTH THROUGH CAPEX AND M&A Delivering Value-Accretive M&A • Strengthening footprint in high-growth Texas market with acquisitions of PB Materials and Rapid Redi-Mix • Significant synergies; Adjusted EPS accretive in 2026 • Strong contribution of $77M to Q3 2026 revenues Rapid Redi-Mix operational sites PB Materials operational sites Amrize operational sites Amrize cement terminals Amrize cement plants • Strengthening Texas footprint with acquisitions of PB Materials in West Texas and Rapid Redi-Mix in Dallas-Fort Worth • Significant synergies achieved YTD; EPS accretive in 2026 • Strong contribution of $77M to Q3 2026 revenues; results outperformed expectations Executing Growth Projects • Invested $262M in Capex in Q3 2026 • On track for ~$900M of Capex in 2026 • Advancing key organic growth projects: Malarkey Shingles Plant, IndianaMidlothian Cement Plant, Texas ✓ Midlothian cement plant in Texas ✓ Exshaw cement plant in Alberta ✓ St. Constant cement plant in Quebec ✓ Aggregates quarry expansions with 6 projects across North America, adding 150M+ tons of reserves ✓ Cement terminal expansions in Memphis, Kansas City, Cincinnati, Columbus, Lubbock ✓ Malarkey shingles plant in Indiana
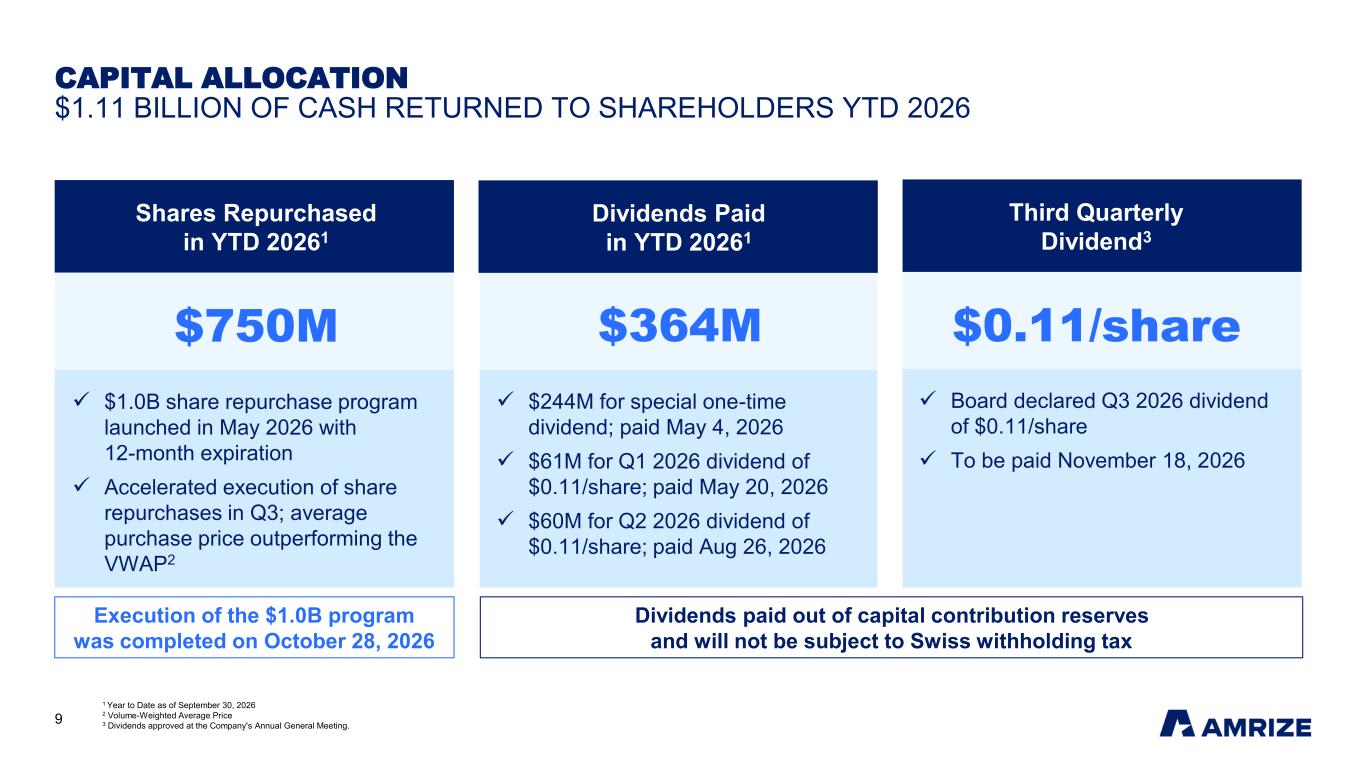
9 CAPITAL ALLOCATION $1.11 BILLION OF CASH RETURNED TO SHAREHOLDERS YTD 2026 $750M Shares Repurchased in YTD 20261 $0.11/share Third Quarterly Dividend3 $364M Dividends Paid in YTD 20261 Dividends paid out of capital contribution reserves and will not be subject to Swiss withholding tax 1 Year to Date as of September 30, 2026 2 Volume-Weighted Average Price 3 Dividends approved at the Company's Annual General Meeting. ✓ $1.0B share repurchase program launched in May 2026 with 12-month expiration ✓ Accelerated execution of share repurchases in Q3; average purchase price outperforming the VWAP2 ✓ $244M for special one-time dividend; paid May 4, 2026 ✓ $61M for Q1 2026 dividend of $0.11/share; paid May 20, 2026 ✓ $60M for Q2 2026 dividend of $0.11/share; paid Aug 26, 2026 ✓ Board declared Q3 2026 dividend of $0.11/share ✓ To be paid November 18, 2026 Execution of the $1.0B program was completed on October 28, 2026
10 Logistics center, Toronto, ON Amrize inside Q3 2026 RESULTS Samuel Poletti, CFO
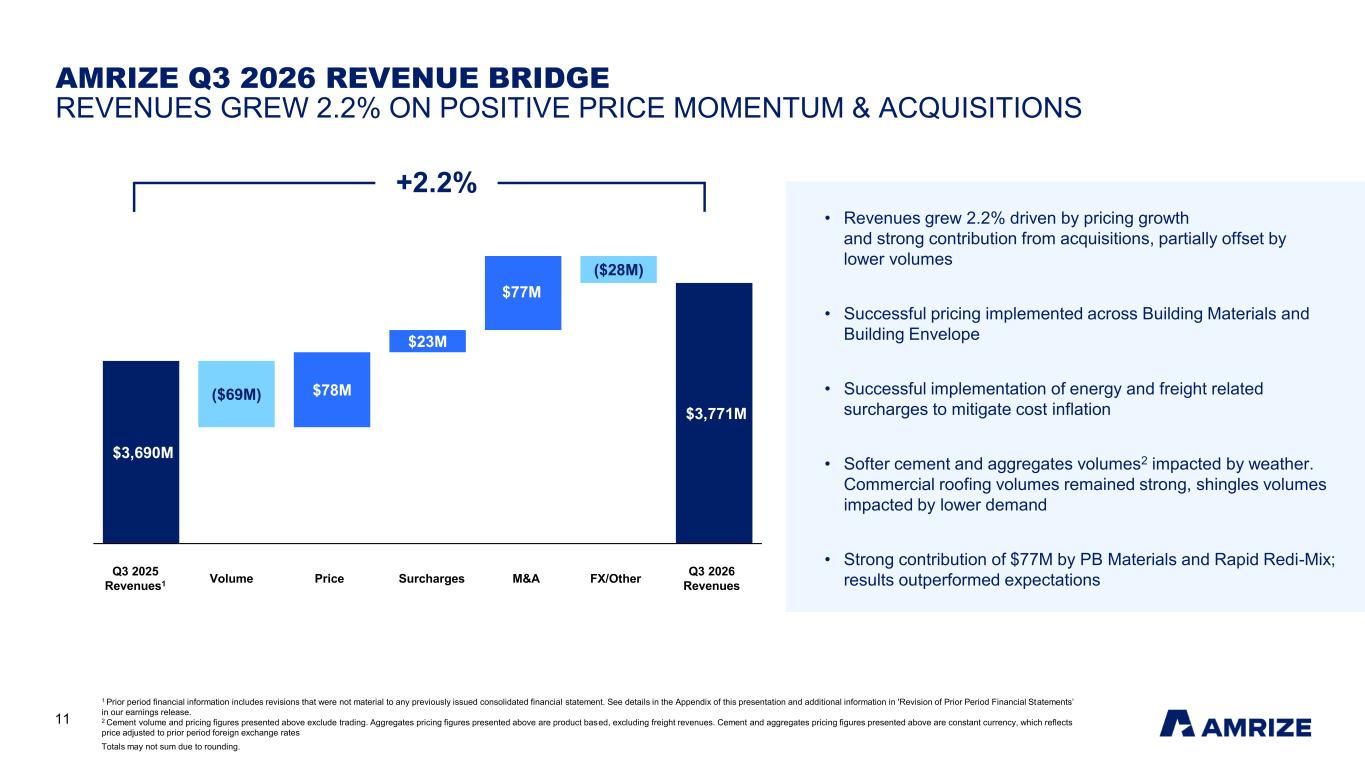
11 AMRIZE Q3 2026 REVENUE BRIDGE REVENUES GREW 2.2% ON POSITIVE PRICE MOMENTUM & ACQUISITIONS Q3 2025 Revenues1 Volume Price Surcharges M&A FX/Other Q3 2026 Revenues +2.2% 1 Prior period financial information includes revisions that were not material to any previously issued consolidated financial statement. See details in the Appendix of this presentation and additional information in 'Revision of Prior Period Financial Statements’ in our earnings release. 2 Cement volume and pricing figures presented above exclude trading. Aggregates pricing figures presented above are product based, excluding freight revenues. Cement and aggregates pricing figures presented above are constant currency, which reflects price adjusted to prior period foreign exchange rates • Revenues grew 2.2% driven by pricing growth and strong contribution from acquisitions, partially offset by lower volumes • Successful pricing implemented across Building Materials and Building Envelope • Successful implementation of energy and freight related surcharges to mitigate cost inflation • Softer cement and aggregates volumes2 impacted by weather. Commercial roofing volumes remained strong, shingles volumes impacted by lower demand • Strong contribution of $77M by PB Materials and Rapid Redi-Mix; results outperformed expectations $3,690M $3,722M $3,771M ($69M) $78M $23M $77M ($28M) 1 2 3 4 5 6 7 Totals may not sum due to rounding.
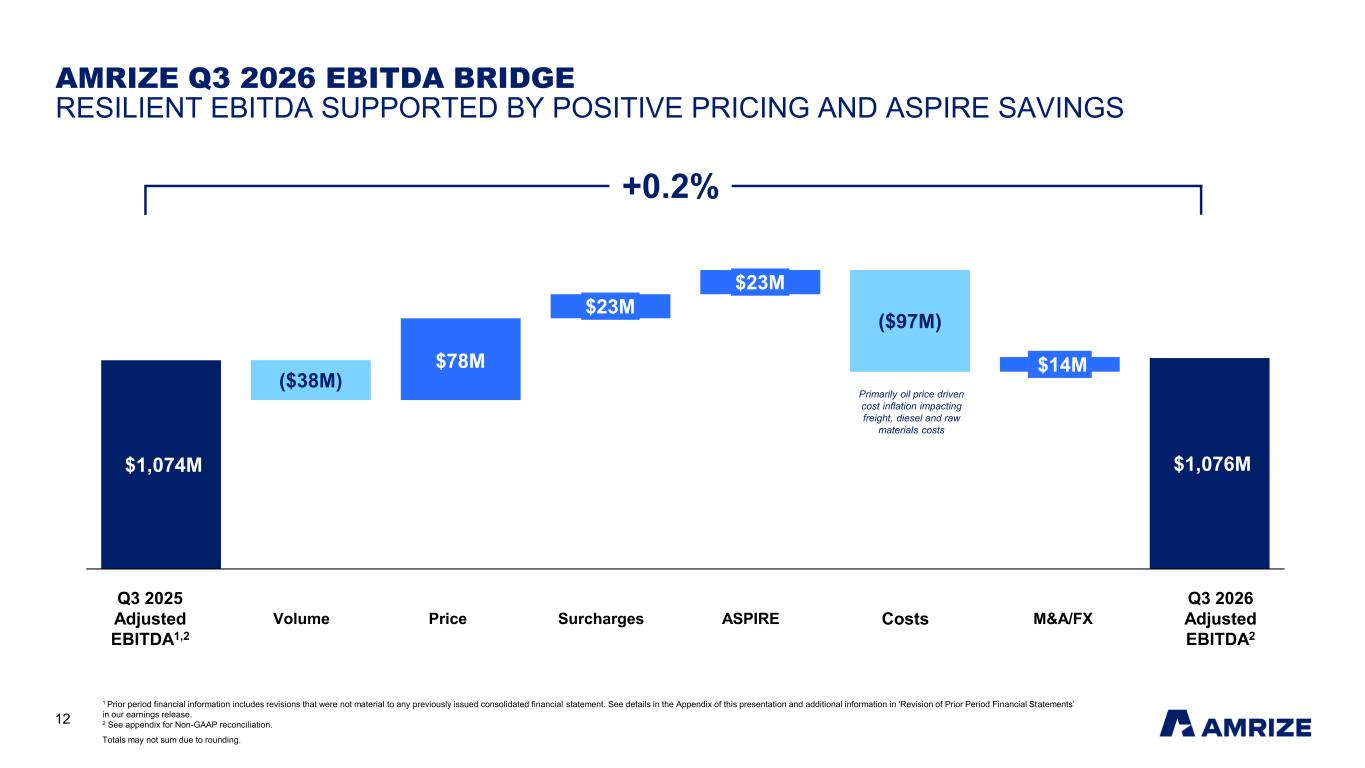
12 +0.2% Q3 2025 Adjusted EBITDA1,2 Volume Price Surcharges ASPIRE Costs M&A/FX Q3 2026 Adjusted EBITDA2 AMRIZE Q3 2026 EBITDA BRIDGE RESILIENT EBITDA SUPPORTED BY POSITIVE PRICING AND ASPIRE SAVINGS 1 Prior period financial information includes revisions that were not material to any previously issued consolidated financial statement. See details in the Appendix of this presentation and additional information in 'Revision of Prior Period Financial Statements’ in our earnings release. 2 See appendix for Non-GAAP reconciliation. $1,074M $1,063M $1,076M ($38M) $78M $23M $23M ($97M) $14M 1 2 3 4 5 6 7 8 Primarily oil price driven cost inflation impacting freight, diesel and raw materials costs Totals may not sum due to rounding.
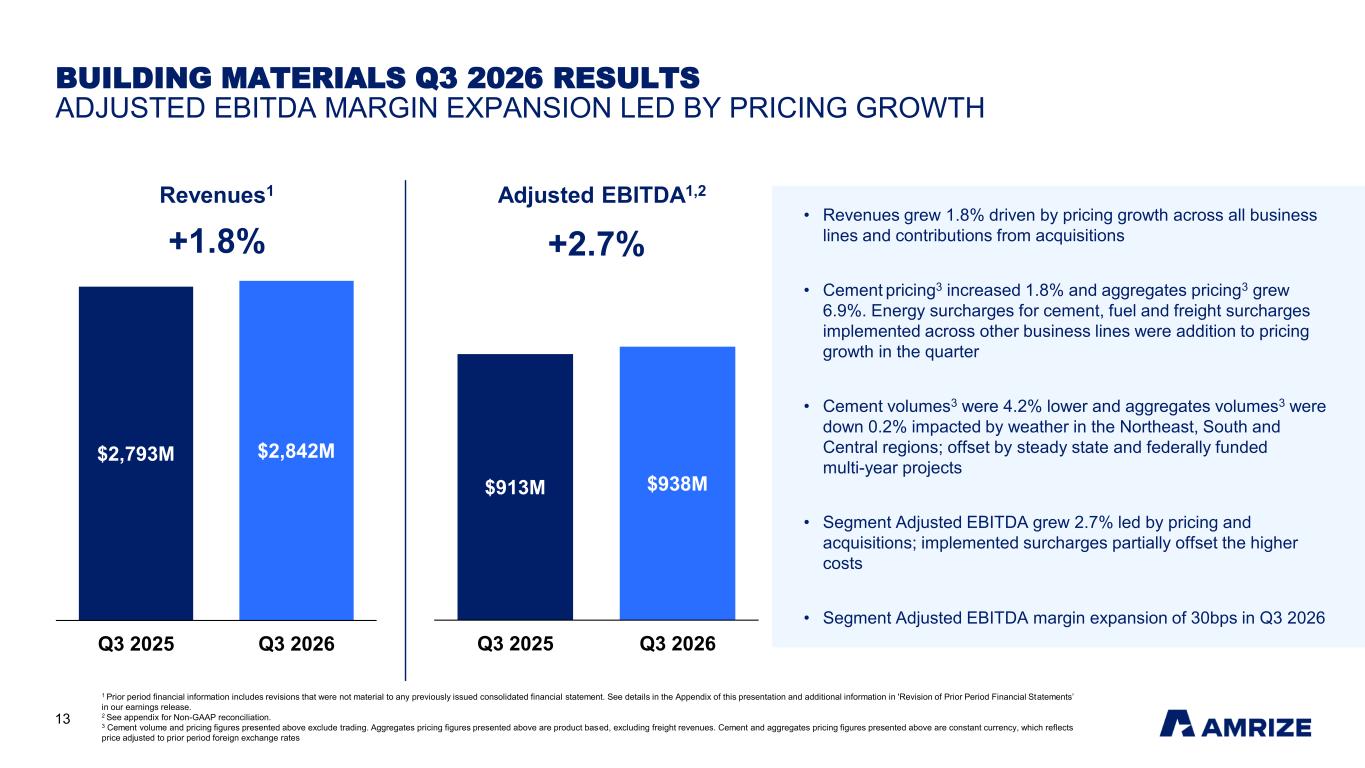
13 BUILDING MATERIALS Q3 2026 RESULTS ADJUSTED EBITDA MARGIN EXPANSION LED BY PRICING GROWTH 1 Prior period financial information includes revisions that were not material to any previously issued consolidated financial statement. See details in the Appendix of this presentation and additional information in 'Revision of Prior Period Financial Statements’ in our earnings release. 2 See appendix for Non-GAAP reconciliation. 3 Cement volume and pricing figures presented above exclude trading. Aggregates pricing figures presented above are product based, excluding freight revenues. Cement and aggregates pricing figures presented above are constant currency, which reflects price adjusted to prior period foreign exchange rates $2,793M $2,842M Q3 2025 Q3 2026 $913M $938M Q3 2025 Q3 2026 Adjusted EBITDA1,2Revenues1 +1.8% +2.7% • Revenues grew 1.8% driven by pricing growth across all business lines and contributions from acquisitions • Cement pricing3 increased 1.8% and aggregates pricing3 grew 6.9%. Energy surcharges for cement, fuel and freight surcharges implemented across other business lines were addition to pricing growth in the quarter • Cement volumes3 were 4.2% lower and aggregates volumes3 were down 0.2% impacted by weather in the Northeast, South and Central regions; offset by steady state and federally funded multi-year projects • Segment Adjusted EBITDA grew 2.7% led by pricing and acquisitions; implemented surcharges partially offset the higher costs • Segment Adjusted EBITDA margin expansion of 30bps in Q3 2026
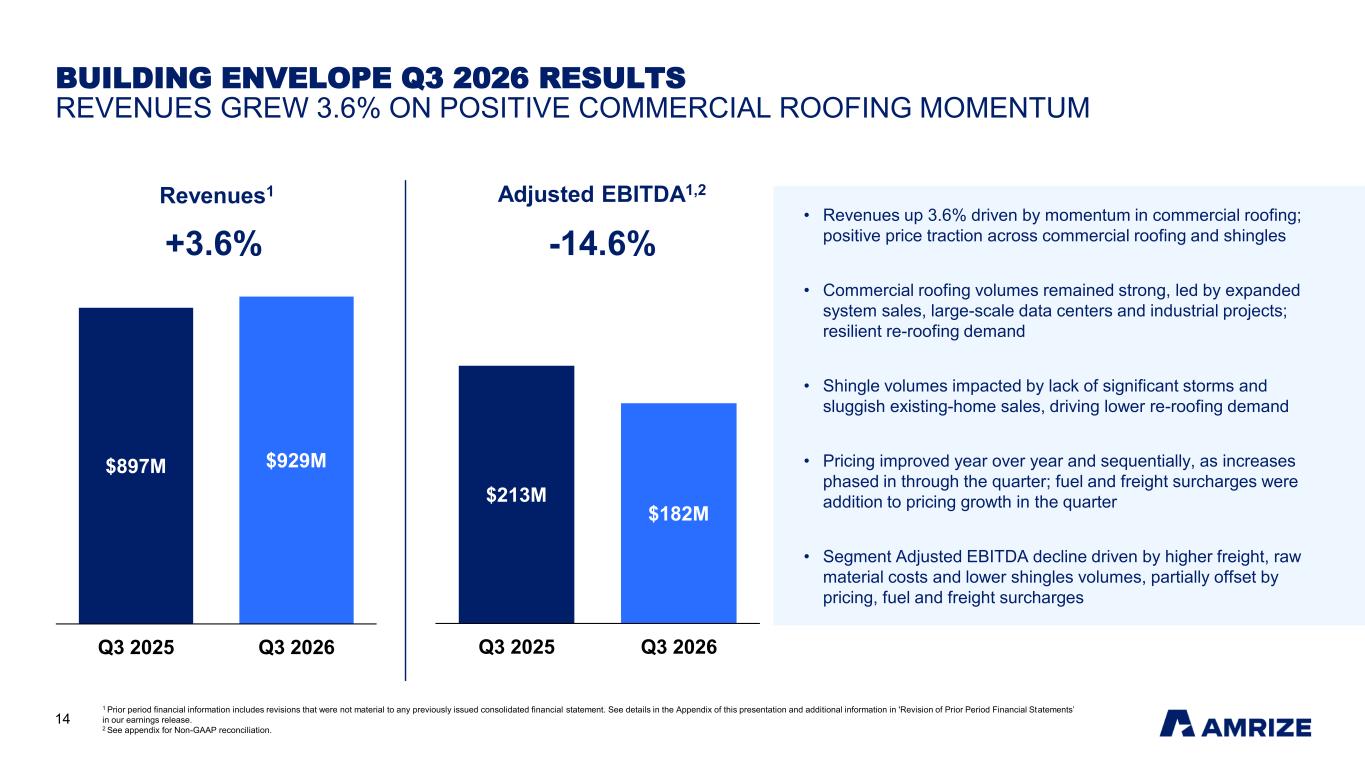
14 BUILDING ENVELOPE Q3 2026 RESULTS REVENUES GREW 3.6% ON POSITIVE COMMERCIAL ROOFING MOMENTUM $897M $929M Q3 2025 Q3 2026 $213M $182M Q3 2025 Q3 2026 1 Prior period financial information includes revisions that were not material to any previously issued consolidated financial statement. See details in the Appendix of this presentation and additional information in 'Revision of Prior Period Financial Statements’ in our earnings release. 2 See appendix for Non-GAAP reconciliation. Adjusted EBITDA1,2Revenues1 +3.6% -14.6% • Revenues up 3.6% driven by momentum in commercial roofing; positive price traction across commercial roofing and shingles • Commercial roofing volumes remained strong, led by expanded system sales, large-scale data centers and industrial projects; resilient re-roofing demand • Shingle volumes impacted by lack of significant storms and sluggish existing-home sales, driving lower re-roofing demand • Pricing improved year over year and sequentially, as increases phased in through the quarter; fuel and freight surcharges were addition to pricing growth in the quarter • Segment Adjusted EBITDA decline driven by higher freight, raw material costs and lower shingles volumes, partially offset by pricing, fuel and freight surcharges
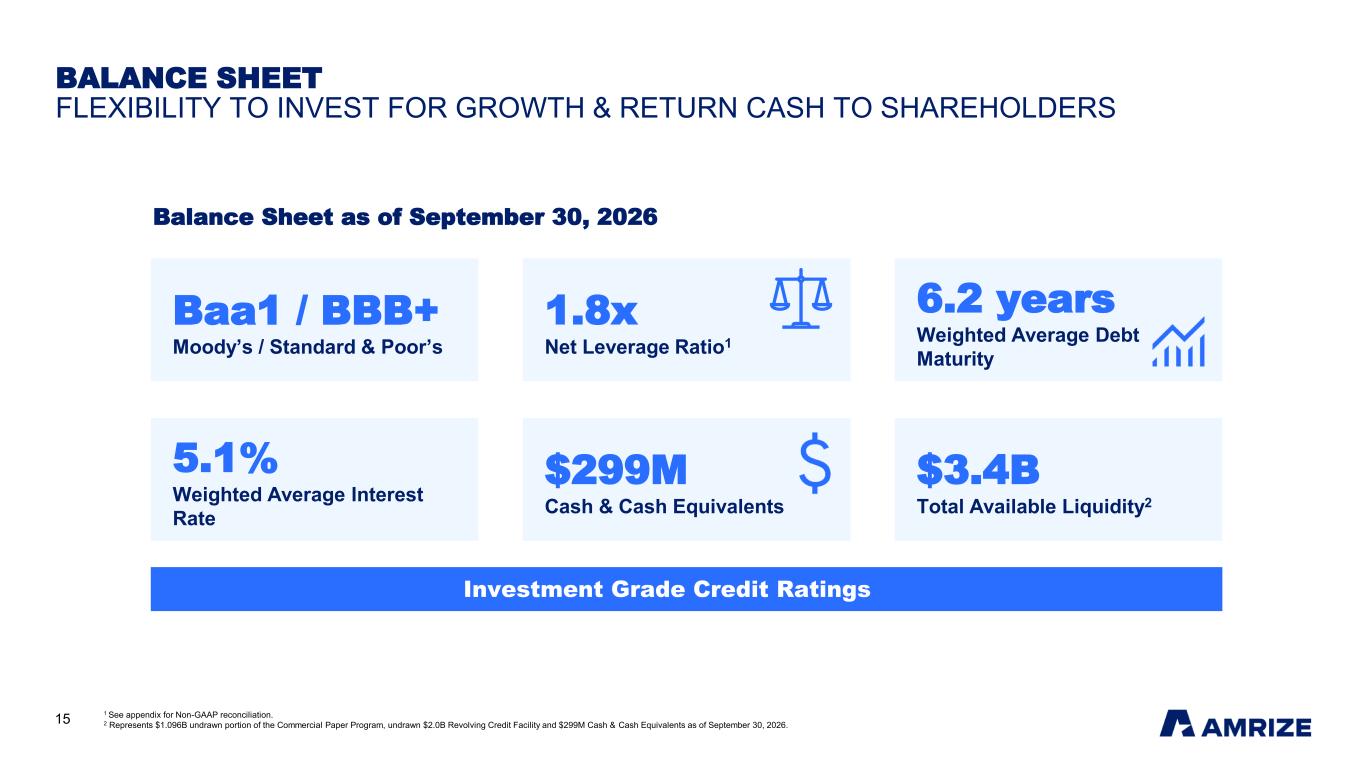
15 BALANCE SHEET FLEXIBILITY TO INVEST FOR GROWTH & RETURN CASH TO SHAREHOLDERS 1 See appendix for Non-GAAP reconciliation. 2 Represents $1.096B undrawn portion of the Commercial Paper Program, undrawn $2.0B Revolving Credit Facility and $299M Cash & Cash Equivalents as of September 30, 2026. 1.8x Net Leverage Ratio1 Balance Sheet as of September 30, 2026 Baa1 / BBB+ Moody’s / Standard & Poor’s 6.2 years Weighted Average Debt Maturity 5.1% Weighted Average Interest Rate $299M Cash & Cash Equivalents $3.4B Total Available Liquidity2 Investment Grade Credit Ratings
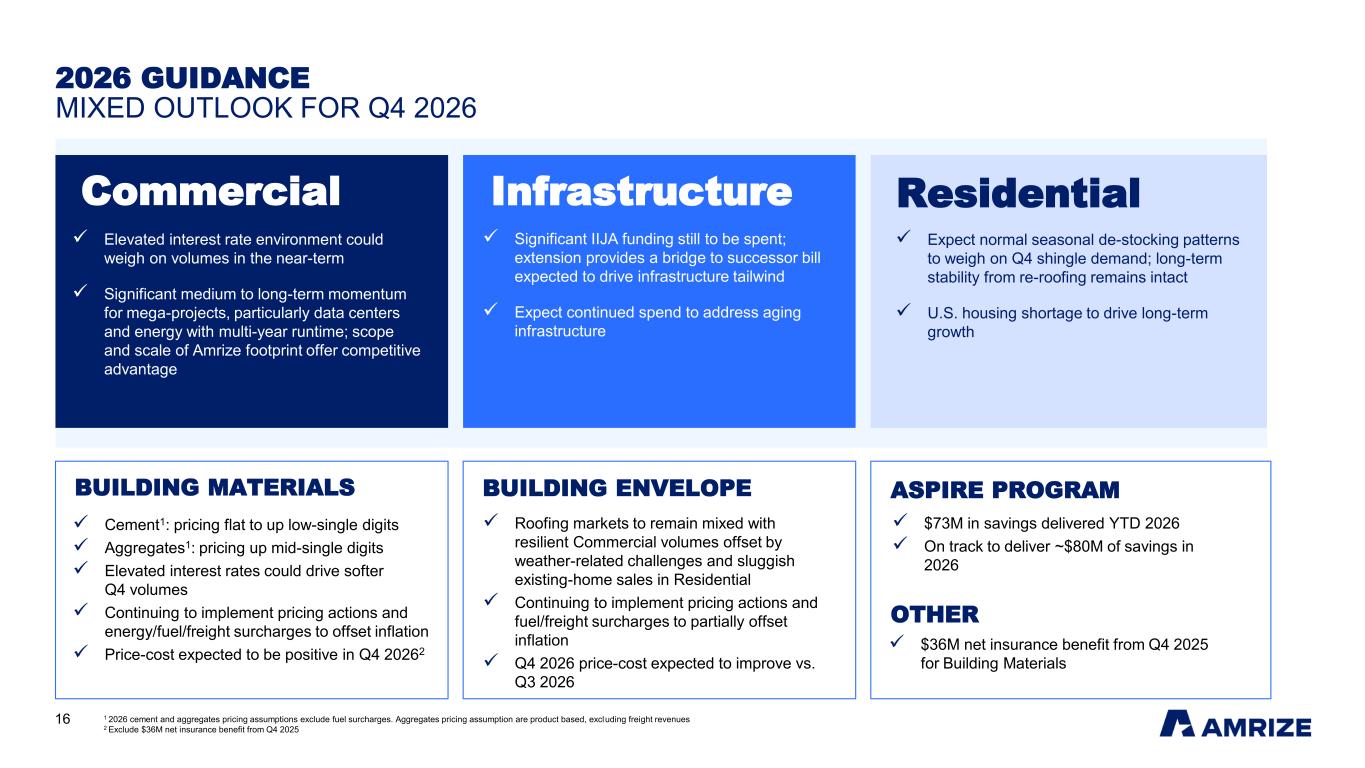
16 2026 GUIDANCE MIXED OUTLOOK FOR Q4 2026 InfrastructureCommercial Residential BUILDING MATERIALS ASPIRE PROGRAMBUILDING ENVELOPE ✓ Expect normal seasonal de-stocking patterns to weigh on Q4 shingle demand; long-term stability from re-roofing remains intact ✓ U.S. housing shortage to drive long-term growth ✓ Significant IIJA funding still to be spent; extension provides a bridge to successor bill expected to drive infrastructure tailwind ✓ Expect continued spend to address aging infrastructure ✓ Elevated interest rate environment could weigh on volumes in the near-term ✓ Significant medium to long-term momentum for mega-projects, particularly data centers and energy with multi-year runtime; scope and scale of Amrize footprint offer competitive advantage ✓ Cement1: pricing flat to up low-single digits ✓ Aggregates1: pricing up mid-single digits ✓ Elevated interest rates could drive softer Q4 volumes ✓ Continuing to implement pricing actions and energy/fuel/freight surcharges to offset inflation ✓ Price-cost expected to be positive in Q4 20262 ✓ Roofing markets to remain mixed with resilient Commercial volumes offset by weather-related challenges and sluggish existing-home sales in Residential ✓ Continuing to implement pricing actions and fuel/freight surcharges to partially offset inflation ✓ Q4 2026 price-cost expected to improve vs. Q3 2026 ✓ $73M in savings delivered YTD 2026 ✓ On track to deliver ~$80M of savings in 2026 OTHER ✓ $36M net insurance benefit from Q4 2025 for Building Materials 1 2026 cement and aggregates pricing assumptions exclude fuel surcharges. Aggregates pricing assumption are product based, excluding freight revenues 2 Exclude $36M net insurance benefit from Q4 2025
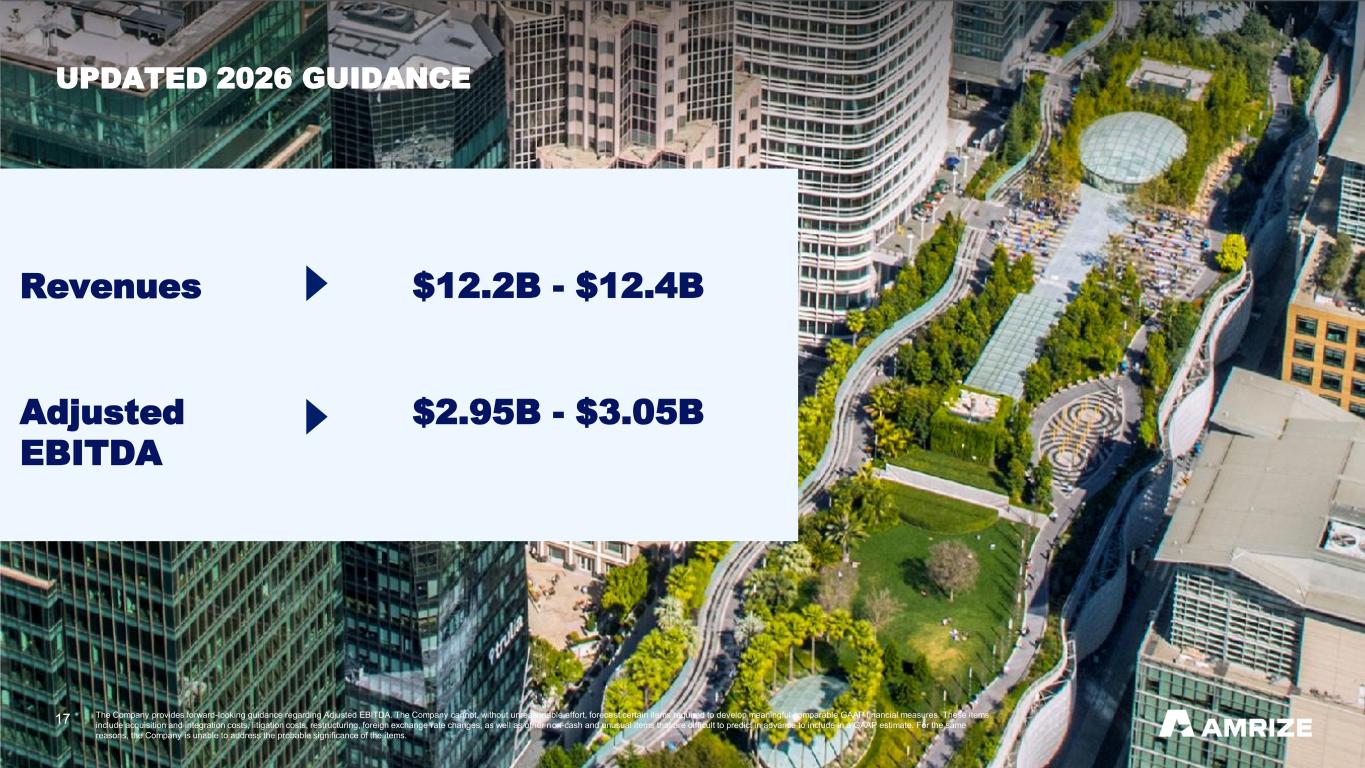
17 UPDATED 2026 GUIDANCE Revenues $12.2B - $12.4B Adjusted EBITDA $2.95B - $3.05B The Company provides forward-looking guidance regarding Adjusted EBITDA. The Company cannot, without unreasonable effort, forecast certain items required to develop meaningful comparable GAAP financial measures. These items include acquisition and integration costs, litigation costs, restructuring, foreign exchange rate changes, as well as other non-cash and unusual items that are difficult to predict in advance to include in a GAAP estimate. For the same reasons, the Company is unable to address the probable significance of the items.
18 One World Trade Center, New York, NY Amrize inside APPENDIX
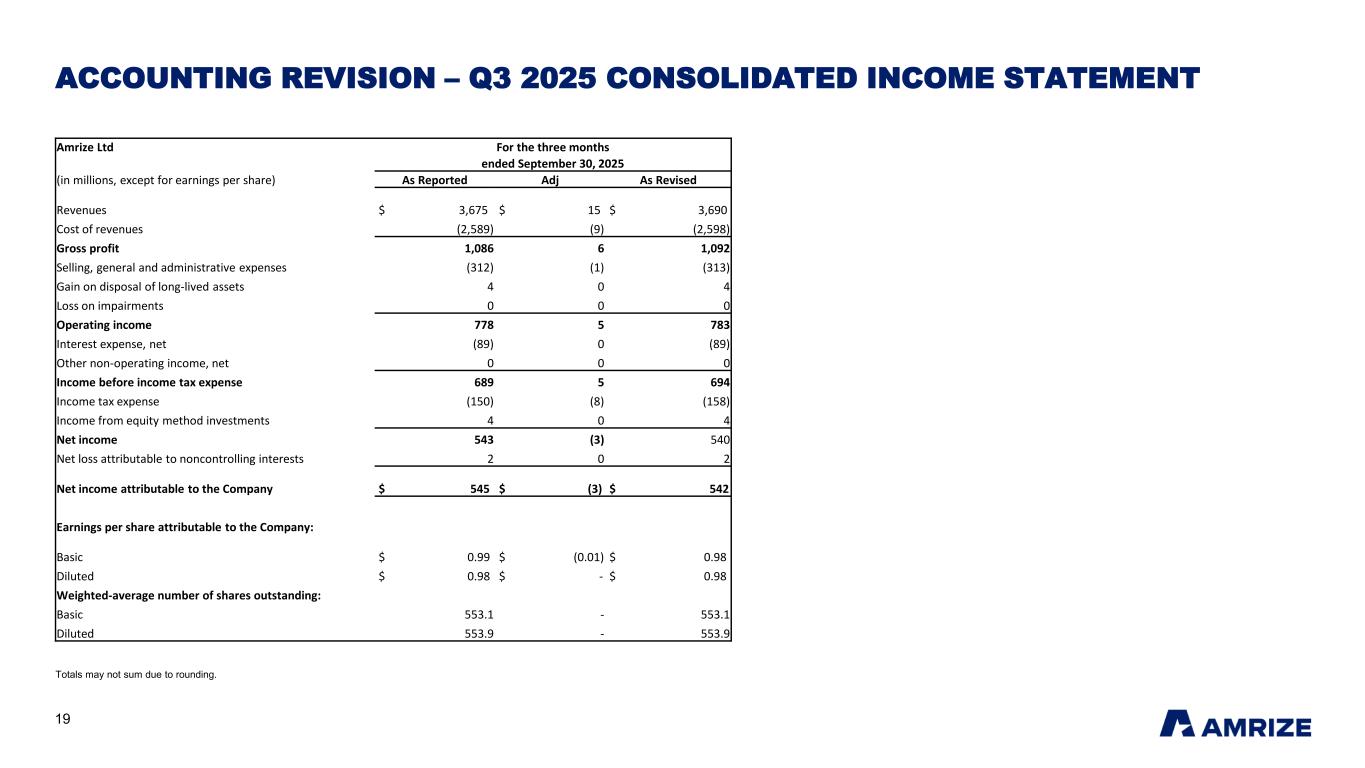
19 ACCOUNTING REVISION – Q3 2025 CONSOLIDATED INCOME STATEMENT Totals may not sum due to rounding. Amrize Ltd For the three months ended September 30, 2025 (in millions, except for earnings per share) As Reported Adj As Revised Revenues $ 3,675 $ 15 $ 3,690 Cost of revenues (2,589) (9) (2,598) Gross profit 1,086 6 1,092 Selling, general and administrative expenses (312) (1) (313) Gain on disposal of long-lived assets 4 0 4 Loss on impairments 0 0 0 Operating income 778 5 783 Interest expense, net (89) 0 (89) Other non-operating income, net 0 0 0 Income before income tax expense 689 5 694 Income tax expense (150) (8) (158) Income from equity method investments 4 0 4 Net income 543 (3) 540 Net loss attributable to noncontrolling interests 2 0 2 Net income attributable to the Company $ 545 $ (3) $ 542 Earnings per share attributable to the Company: Basic $ 0.99 $ (0.01) $ 0.98 Diluted $ 0.98 $ - $ 0.98 Weighted-average number of shares outstanding: Basic 553.1 - 553.1 Diluted 553.9 - 553.9
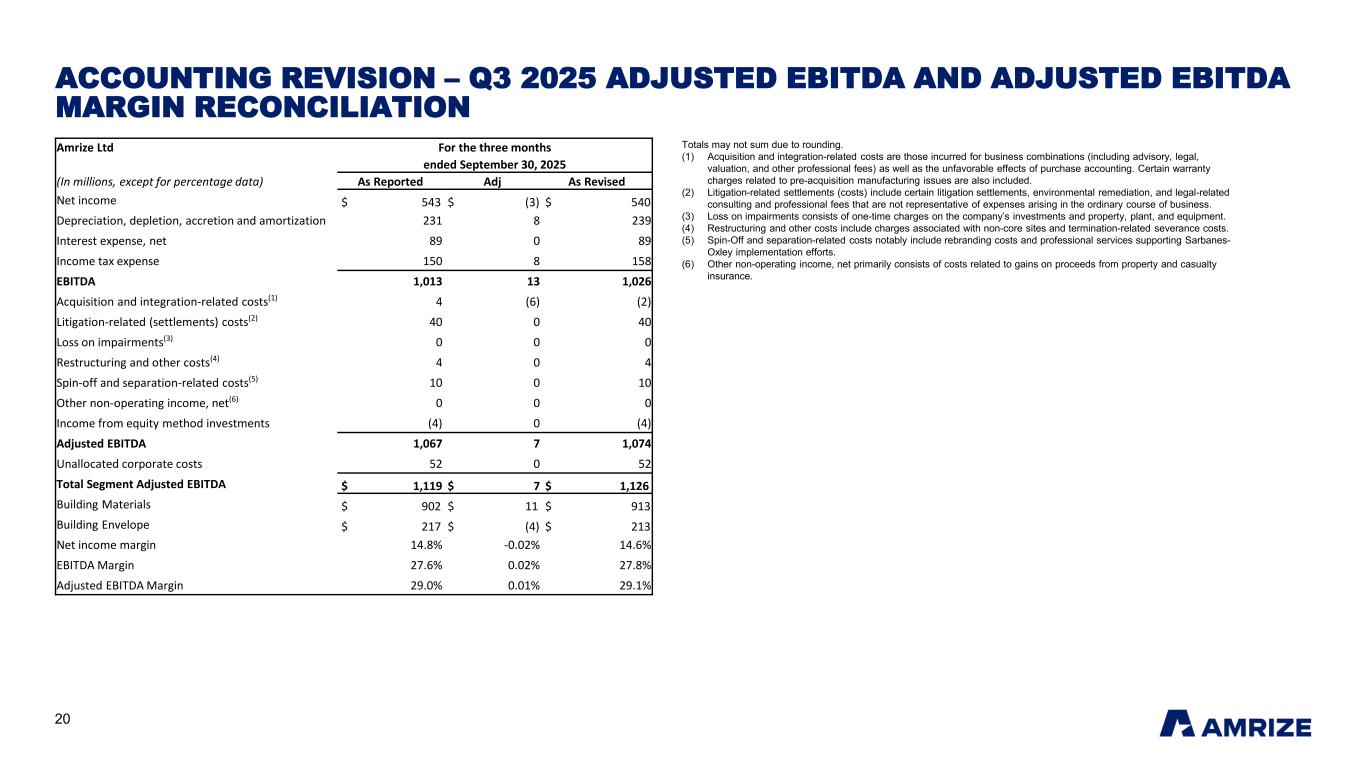
20 ACCOUNTING REVISION – Q3 2025 ADJUSTED EBITDA AND ADJUSTED EBITDA MARGIN RECONCILIATION Totals may not sum due to rounding. (1) Acquisition and integration-related costs are those incurred for business combinations (including advisory, legal, valuation, and other professional fees) as well as the unfavorable effects of purchase accounting. Certain warranty charges related to pre-acquisition manufacturing issues are also included. (2) Litigation-related settlements (costs) include certain litigation settlements, environmental remediation, and legal-related consulting and professional fees that are not representative of expenses arising in the ordinary course of business. (3) Loss on impairments consists of one-time charges on the company’s investments and property, plant, and equipment. (4) Restructuring and other costs include charges associated with non-core sites and termination-related severance costs. (5) Spin-Off and separation-related costs notably include rebranding costs and professional services supporting Sarbanes- Oxley implementation efforts. (6) Other non-operating income, net primarily consists of costs related to gains on proceeds from property and casualty insurance. Amrize Ltd For the three months ended September 30, 2025 (In millions, except for percentage data) As Reported Adj As Revised Net income $ 543 $ (3) $ 540 Depreciation, depletion, accretion and amortization 231 8 239 Interest expense, net 89 0 89 Income tax expense 150 8 158 EBITDA 1,013 13 1,026 Acquisition and integration-related costs(1) 4 (6) (2) Litigation-related (settlements) costs(2) 40 0 40 Loss on impairments(3) 0 0 0 Restructuring and other costs(4) 4 0 4 Spin-off and separation-related costs(5) 10 0 10 Other non-operating income, net(6) 0 0 0 Income from equity method investments (4) 0 (4) Adjusted EBITDA 1,067 7 1,074 Unallocated corporate costs 52 0 52 Total Segment Adjusted EBITDA $ 1,119 $ 7 $ 1,126 Building Materials $ 902 $ 11 $ 913 Building Envelope $ 217 $ (4) $ 213 Net income margin 14.8% -0.02% 14.6% EBITDA Margin 27.6% 0.02% 27.8% Adjusted EBITDA Margin 29.0% 0.01% 29.1%
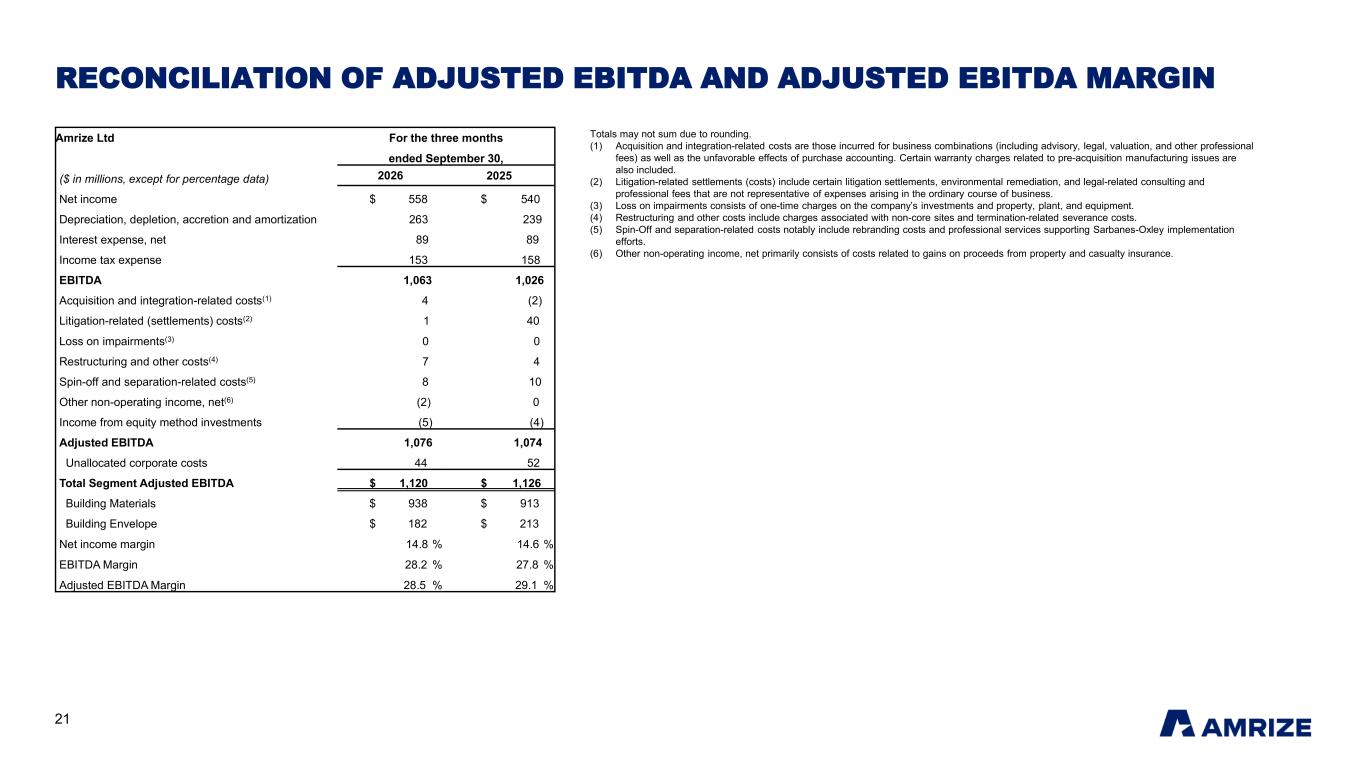
21 RECONCILIATION OF ADJUSTED EBITDA AND ADJUSTED EBITDA MARGIN Totals may not sum due to rounding. (1) Acquisition and integration-related costs are those incurred for business combinations (including advisory, legal, valuation, and other professional fees) as well as the unfavorable effects of purchase accounting. Certain warranty charges related to pre-acquisition manufacturing issues are also included. (2) Litigation-related settlements (costs) include certain litigation settlements, environmental remediation, and legal-related consulting and professional fees that are not representative of expenses arising in the ordinary course of business. (3) Loss on impairments consists of one-time charges on the company’s investments and property, plant, and equipment. (4) Restructuring and other costs include charges associated with non-core sites and termination-related severance costs. (5) Spin-Off and separation-related costs notably include rebranding costs and professional services supporting Sarbanes-Oxley implementation efforts. (6) Other non-operating income, net primarily consists of costs related to gains on proceeds from property and casualty insurance. Amrize Ltd For the three months ended September 30, ($ in millions, except for percentage data) 2026 2025 Net income $ 558 $ 540 Depreciation, depletion, accretion and amortization 263 239 Interest expense, net 89 89 Income tax expense 153 158 EBITDA 1,063 1,026 Acquisition and integration-related costs(1) 4 (2) Litigation-related (settlements) costs(2) 1 40 Loss on impairments(3) 0 0 Restructuring and other costs(4) 7 4 Spin-off and separation-related costs(5) 8 10 Other non-operating income, net(6) (2) 0 Income from equity method investments (5) (4) Adjusted EBITDA 1,076 1,074 Unallocated corporate costs 44 52 Total Segment Adjusted EBITDA $ 1,120 $ 1,126 Building Materials $ 938 $ 913 Building Envelope $ 182 $ 213 Net income margin 14.8 % 14.6 % EBITDA Margin 28.2 % 27.8 % Adjusted EBITDA Margin 28.5 % 29.1 %
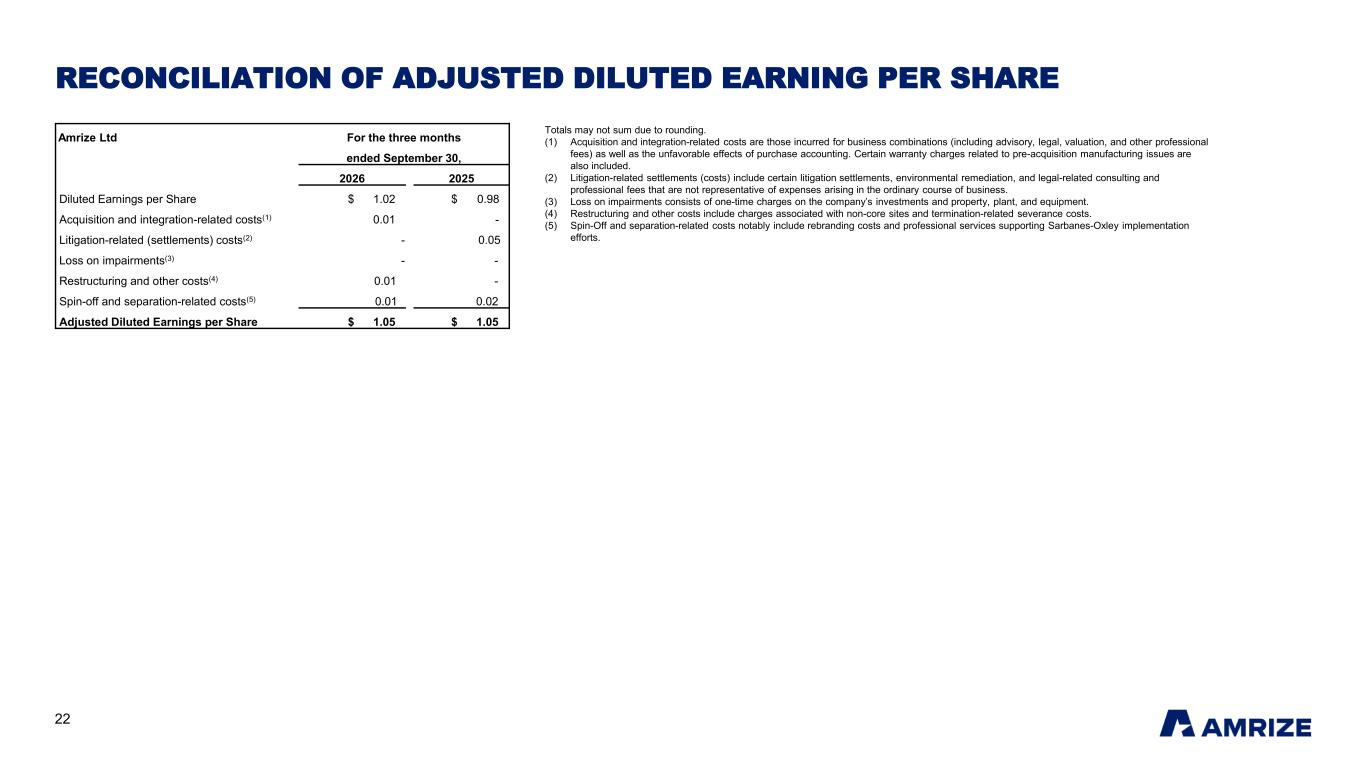
22 RECONCILIATION OF ADJUSTED DILUTED EARNING PER SHARE Totals may not sum due to rounding. (1) Acquisition and integration-related costs are those incurred for business combinations (including advisory, legal, valuation, and other professional fees) as well as the unfavorable effects of purchase accounting. Certain warranty charges related to pre-acquisition manufacturing issues are also included. (2) Litigation-related settlements (costs) include certain litigation settlements, environmental remediation, and legal-related consulting and professional fees that are not representative of expenses arising in the ordinary course of business. (3) Loss on impairments consists of one-time charges on the company’s investments and property, plant, and equipment. (4) Restructuring and other costs include charges associated with non-core sites and termination-related severance costs. (5) Spin-Off and separation-related costs notably include rebranding costs and professional services supporting Sarbanes-Oxley implementation efforts. Amrize Ltd For the three months ended September 30, 2026 2025 Diluted Earnings per Share $ 1.02 $ 0.98 Acquisition and integration-related costs(1) 0.01 - Litigation-related (settlements) costs(2) - 0.05 Loss on impairments(3) - - Restructuring and other costs(4) 0.01 - Spin-off and separation-related costs(5) 0.01 0.02 Adjusted Diluted Earnings per Share $ 1.05 $ 1.05
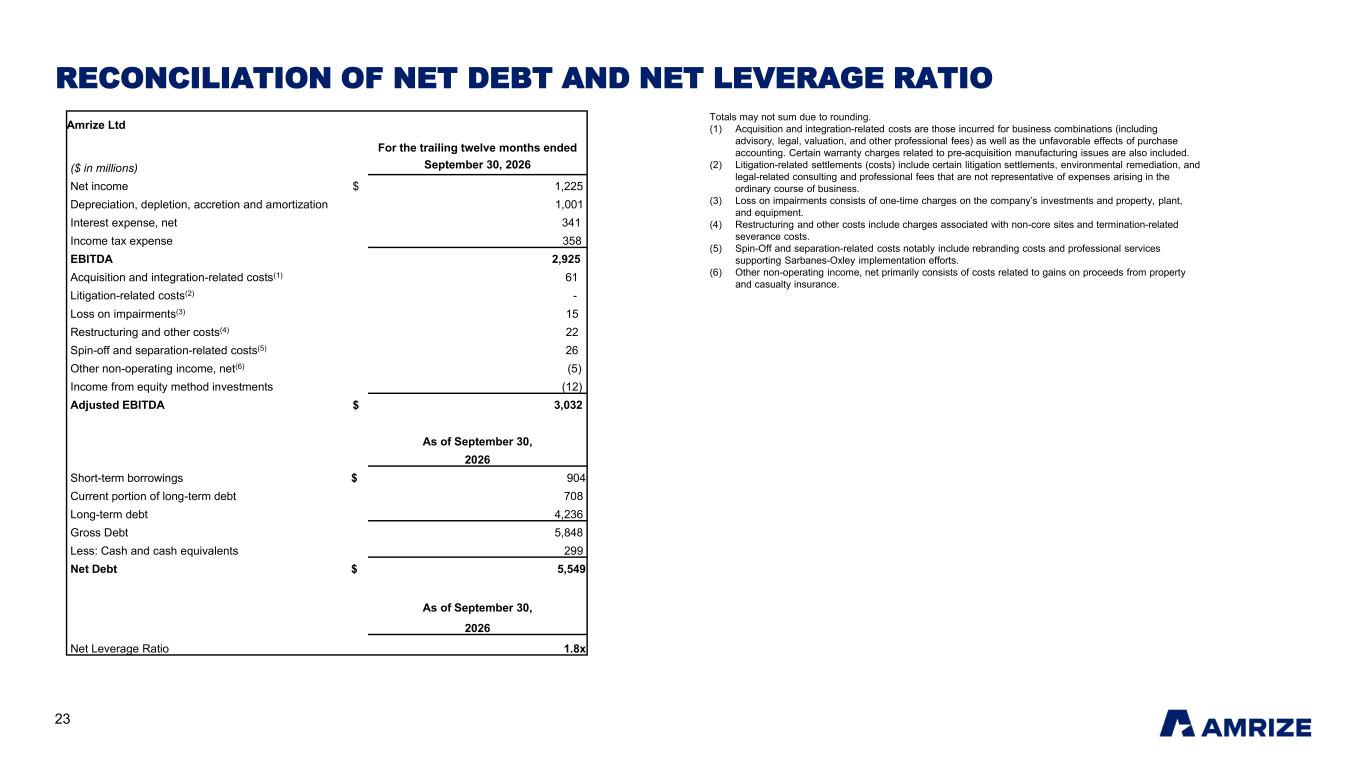
23 RECONCILIATION OF NET DEBT AND NET LEVERAGE RATIO Totals may not sum due to rounding. (1) Acquisition and integration-related costs are those incurred for business combinations (including advisory, legal, valuation, and other professional fees) as well as the unfavorable effects of purchase accounting. Certain warranty charges related to pre-acquisition manufacturing issues are also included. (2) Litigation-related settlements (costs) include certain litigation settlements, environmental remediation, and legal-related consulting and professional fees that are not representative of expenses arising in the ordinary course of business. (3) Loss on impairments consists of one-time charges on the company’s investments and property, plant, and equipment. (4) Restructuring and other costs include charges associated with non-core sites and termination-related severance costs. (5) Spin-Off and separation-related costs notably include rebranding costs and professional services supporting Sarbanes-Oxley implementation efforts. (6) Other non-operating income, net primarily consists of costs related to gains on proceeds from property and casualty insurance. Amrize Ltd For the trailing twelve months ended ($ in millions) September 30, 2026 Net income $ 1,225 Depreciation, depletion, accretion and amortization 1,001 Interest expense, net 341 Income tax expense 358 EBITDA 2,925 Acquisition and integration-related costs(1) 61 Litigation-related costs(2) - Loss on impairments(3) 15 Restructuring and other costs(4) 22 Spin-off and separation-related costs(5) 26 Other non-operating income, net(6) (5) Income from equity method investments (12) Adjusted EBITDA $ 3,032 As of September 30, 2026 Short-term borrowings $ 904 Current portion of long-term debt 708 Long-term debt 4,236 Gross Debt 5,848 Less: Cash and cash equivalents 299 Net Debt $ 5,549 As of September 30, 2026 Net Leverage Ratio 1.8x
© 2026 Amrize. All rights reserved.